How your mortgage became the tool to fight inflation
Australia's mortgage structure means rate rises hit one-third of households hardest — and that's not a bug in the system, it's how it was built.
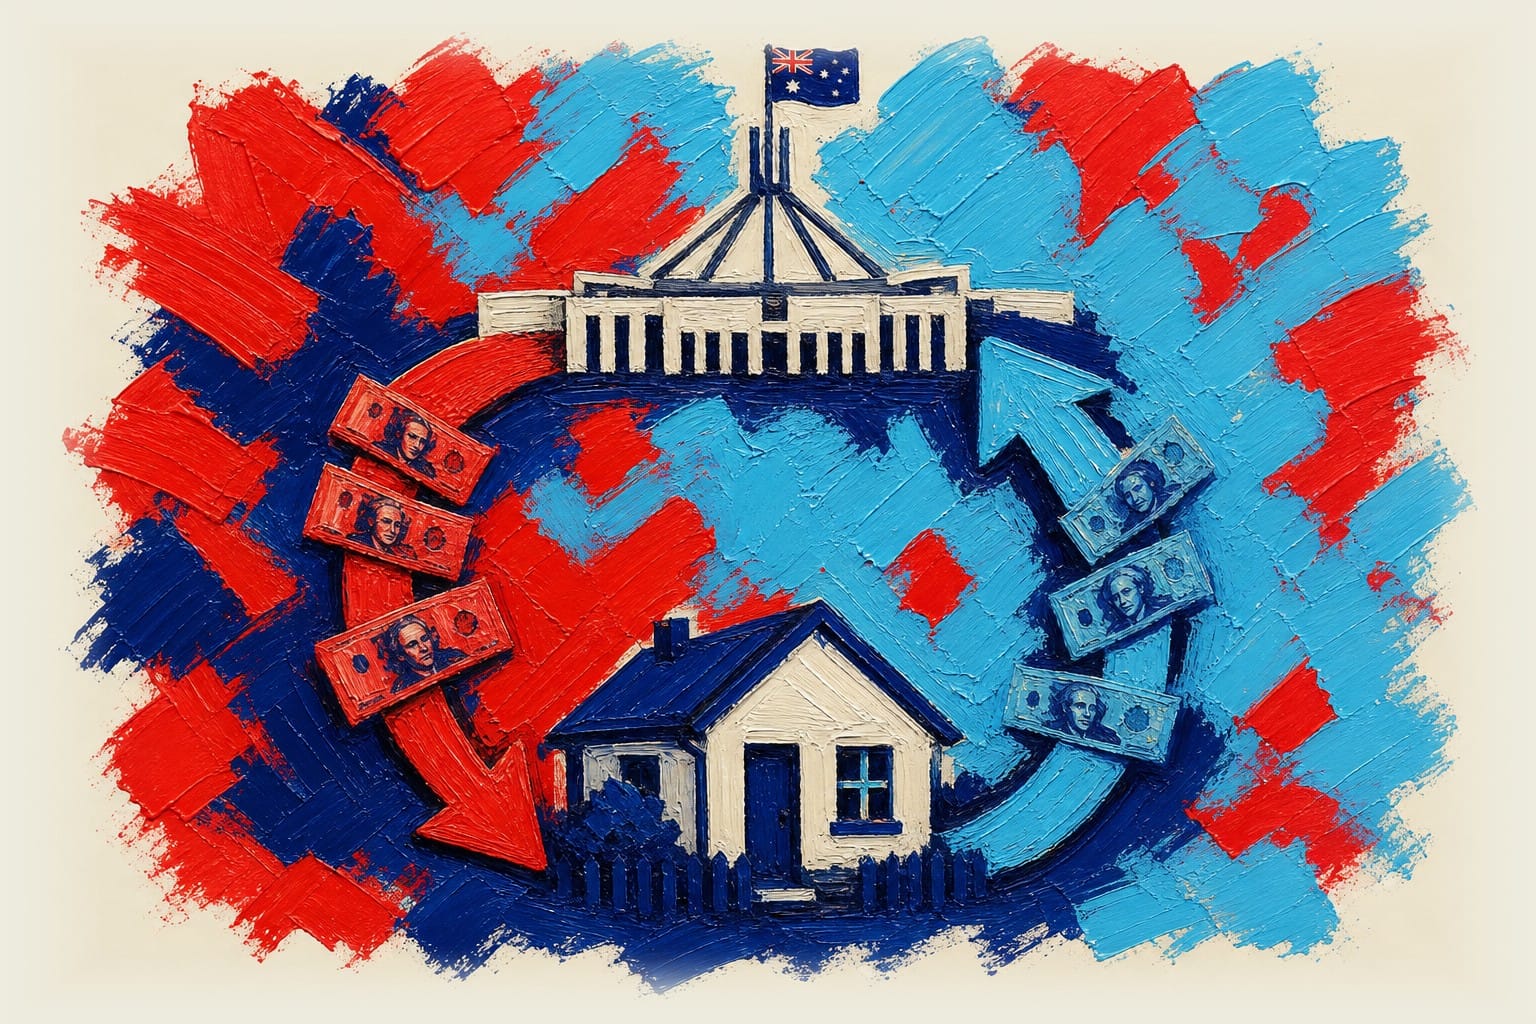
There is a particular cruelty to the way inflation is brought under control in Australia. The government spends. The Reserve Bank raises rates. And the person with a variable mortgage wakes up to find their repayments have climbed again, not because of anything they did, but because they are, structurally, the most convenient instrument available for squeezing money out of the economy.
The mechanism rewards holding, not selling
The mechanism is not complicated, but it is worth spelling out because it gets lost in the public conversation, where rate rises tend to be presented as something the RBA does to inflation, rather than something borrowers absorb on the economy's behalf.
When government borrows and injects money into circulation — through welfare payments, infrastructure contracts, subsidies, wage bills — it adds to aggregate demand. More money chasing the same amount of goods pushes prices up. The RBA's job is to offset that pressure, and it has one primary tool: the cash rate. Raise it, and borrowing becomes more expensive. More expensive borrowing means households and businesses spend less. Less spending means less upward pressure on prices. The inflation comes down — but the cost of bringing it down has been borne by whoever holds floating-rate debt.
Australia's mortgage market makes this transmission unusually direct and unusually painful. Unlike in the United States and much of Europe, where thirty-year fixed-rate mortgages are the norm and households can lock in for decades, most Australian mortgages are variable or fixed only for short terms. When the RBA moves, borrowers feel it almost immediately. That structural feature is not incidental; it is why the cash rate works as quickly as it does here. The speed of transmission is the point. But it means the burden falls on a specific group rather than dispersing across the economy evenly.
The speed of transmission is the point. But it means the burden falls on a specific group rather than dispersing across the economy evenly.
One third of households carry the weight for all of them
Consider what that group looks like. About a third of Australian households are owner-occupiers with a mortgage. Another third rent. Another third own outright. When rates rise, the mortgage-holding third absorbs the hit. Renters are somewhat insulated in the short run, though landlords eventually pass costs through. Outright owners are largely unaffected, or may even benefit if they hold savings earning interest. The response to inflation is calibrated to produce economy-wide restraint, but the instrument that delivers it is aimed squarely at one cohort.
This is not an argument that the RBA should stop raising rates when inflation is high. The alternative — doing nothing and allowing inflation to run — destroys purchasing power across the entire population, and does the most damage to people with the least capacity to absorb it. As we've noted before, the basic arithmetic of rate rises and inflation is already poorly understood by most Australians, and the case for central bank discipline is not weaker because it is unpopular.
Fiscal policy is doing the damage; monetary policy is taking the blame
The real question is about who does the work of controlling inflation, government spending decisions (fiscal policy) or the Reserve Bank's interest rate decisions (monetary policy). When government spending pushes prices up and interest rates are left to do all the counteracting, it's borrowers, particularly mortgage holders, who end up paying for the government's choices. A fairer approach would have the government pull its own weight by spending less or taxing more, rather than leaving the RBA to absorb the whole shock on its own. That conversation has been made harder by the structural pressures on the budget: Australia's debt has surpassed $1 trillion, and as Treasury has flagged in its recent intergenerational work, the costs associated with an ageing population, defence, and the energy transition mean government spending is unlikely to fall as a share of GDP any time soon.
There is also a legitimate question about whether the RBA's tools are well matched to the kind of inflation they are being asked to fight. Rate rises are designed to suppress demand. But if inflation is driven partly by supply constraints — energy costs, construction bottlenecks, global commodity shocks — then crushing household spending does not fix the underlying problem. It just makes the cure expensive for people who did not cause the disease. We've examined the RBA's rate decisions and what actually drives them and the picture is messier than a clean demand-suppression story suggests.
None of this resolves neatly. The RBA cannot refuse to act because the fiscal settings are loose. It cannot choose a different tool because it does not have one. And borrowers cannot opt out of the mechanism they happen to sit inside. What they can do is understand it clearly: when government borrows and spends, and the reserve bank responds, the mortgage on your home is not collateral damage. It is the instrument. That is the system working as designed — and the design is one worth examining.
Sources
ABC News — ASX gains 1 per cent as oil tumbles on peace hopes
The Bearing — The Five Transitions: Treasury Warns of Converging Pressures on Budget and Growth
The Bearing — RBA signals rate rise to cool jobs market. But hot jobs are good jobs.
Frequently Asked Questions
Why do mortgage holders pay the price when the government spends too much?
When government borrowing pushes money into the economy and drives inflation, the RBA raises interest rates to suppress demand. Because most Australian mortgages are variable rate, those repayments rise almost immediately — making mortgage holders the primary channel through which the economy is cooled, regardless of whether they contributed to the inflationary pressure.
Why does Australia feel rate rises faster than countries like the US?
In the United States, thirty-year fixed-rate mortgages are standard, so most households are insulated from rate changes for decades. In Australia, variable and short-term fixed mortgages dominate, meaning RBA rate decisions pass through to household repayments within weeks. That speed is why the cash rate is effective here — but it concentrates the pain.
What would a fairer way to fight inflation look like?
A more balanced approach would have the government moderating its own spending — reducing the fiscal stimulus that feeds inflationary pressure in the first place — rather than leaving the RBA to act as the sole brake on the economy. That would spread the adjustment burden more evenly instead of concentrating it on the third of households with a mortgage.
Does raising interest rates actually fix inflation caused by supply problems?
Not directly. Rate rises are designed to suppress consumer demand, but when inflation is driven by supply constraints — such as energy costs, construction shortages, or global commodity shocks — squeezing household spending does not resolve the underlying shortage. It reduces price pressure at the cost of household income without addressing the cause.
Are renters protected when interest rates go up?
Renters are partially insulated in the short run because their housing costs are not directly tied to the cash rate. Over time, however, landlords tend to pass higher mortgage costs through in the form of rent increases, so renters bear a lagged and indirect share of the adjustment.